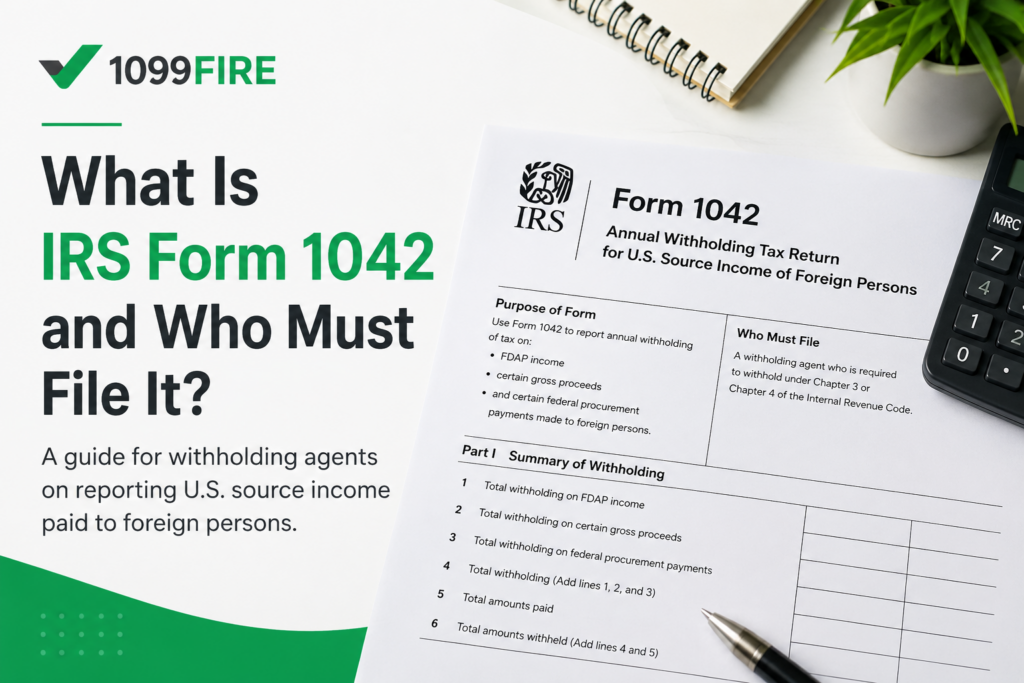
What Is IRS Form 1042 and Who Must File It?
IRS Form 1042, Annual Withholding Tax Return for U.S. Source Income of Foreign Persons, is used to report certain payments

Explore guidance on Form 1042-S and U.S. information reporting requirements for payments made to foreign persons. This section covers withholding agent responsibilities, Form 1042 and 1042-S filing requirements, income and exemption codes, tax treaty considerations, FATCA-related reporting, foreign contractor payments, and common cross-border reporting scenarios. You’ll also find resources on filing deadlines, corrections, recipient statements, documentation such as Forms W-8, and other compliance issues that can affect businesses and organizations making U.S.-source payments to non-U.S. recipients.
IRS Form 1042, Annual Withholding Tax Return for U.S. Source Income of Foreign Persons, is used to report certain payments
Hiring international contractors requires following IRS reporting rules. Whether you issue Form 1099-NEC or Form 1042-S depends on the contractor’s
The United States has income tax treaties with many countries that may allow nonresident aliens to claim a reduced withholding
U.S. businesses sometimes pay independent contractors, vendors, or professionals in a currency other than U.S. dollars. If those payments are
When it comes to withholding and reporting payments to foreign persons, many filers focus on Form 1042-S—the statement issued to
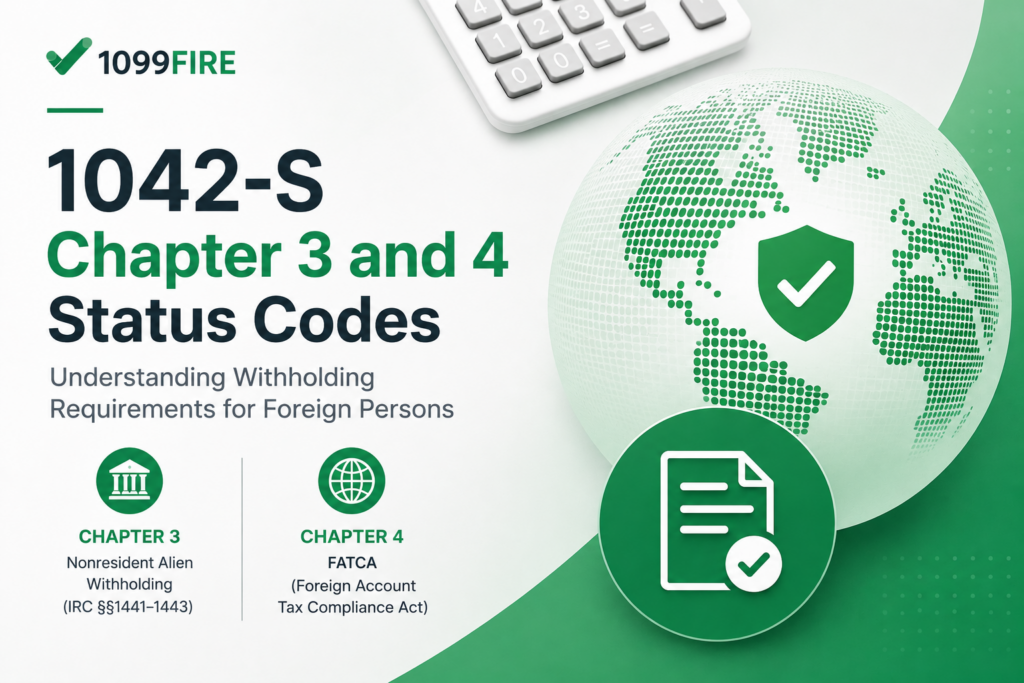
On Form 1042-S, the Chapter 3 Status Code (Box 12) and Chapter 4 Status Code (Box 13i) are used to
When working with independent contractors, one of the most important tax compliance steps is ensuring that payments are reported on
Reconciling Form 1042 (Annual Withholding Tax Return for U.S. Source Income of Foreign Persons) with your Form 1042-S filings is
Casinos in the U.S. have specific IRS reporting obligations when it comes to gambling winnings. The two primary forms involved
IRS Form 1040-NR is the U.S. tax return used by nonresident aliens to report U.S.-source income, calculate taxes owed, or
Navigating U.S. tax reporting rules for cross-border payments can be tricky — especially when deciding whether to issue a Form
Foreign athletes and entertainers who earn income in the United States follow special tax withholding and reporting rules. Payers use
The Foreign Account Tax Compliance Act (FATCA) is a U.S. law created to prevent tax evasion. It requires foreign financial
Nonresident aliens (NRAs) can claim a withholding tax credit on Form 1040-NR, U.S. Nonresident Alien Income Tax Return using the
An orchestra must file Form 1042-S when it pays U.S.-source income to nonresident aliens. These can include performers, conductors, guest
When working with non-US residents or foreign contractors, businesses often wonder whether they need to issue Form 1099-NEC. The general
When it comes to gambling winnings, the tax reporting requirements differ depending on whether the winner is a U.S. resident
When a non-U.S. resident (nonresident alien) wins a gambling prize in the United States, specific tax rules apply. Winnings are
IntroductionIRS Form 1042-S is used to report certain U.S.-source income paid to foreign persons, along with any U.S. federal tax
The primary purpose of Chapter 4 (the Foreign Account Tax Compliance Act (FATCA)) was to address the issue of U.S.
Yes. If you are required to file Form 1042-S, you generally must also file Form 1042. These forms work together
A qualified intermediary (QI) for a 1042-S form is an intermediary, usually a foreign financial institution, that has entered into
When a foreign tourist wins money at a U.S. casino, the IRS requires reporting through Form 1042-S. Gambling winnings for
When a U.S. publisher pays royalties to a foreign author, those payments count as U.S.-source income. The publisher must report
To get a refund from the total withholding credit on Form 1042-S, follow these steps: 1. Complete Your U.S. Tax
Forms 1042 and 1042-S are both related to tax reporting for payments made to foreign persons, but they serve different
A withholding agent is any person, business, or organization (U.S. or foreign) that is responsible for paying income to a
It’s a common question: you received Copy B of IRS Form 1042-S in the mail or by email. The form
The Foreign Account Tax Compliance Act (FATCA) adds another layer of complexity to the already challenging financial situations faced by
The expansion of Form 1042-S has created a broad definition of who may be required to file. This expansion stems
A Global Intermediary Identification Number (GIIN) is a unique identifier issued by the IRS to financial institutions and other entities
When you pay U.S. source income to foreign persons—such as nonresident aliens or foreign entities—the IRS requires withholding and reporting
Foreign workers, students, and other non-resident aliens are subject to U.S. tax withholding when they work in the United States.
The Foreign Account Tax Compliance Act (FATCA) was introduced in 2010 to prevent tax evasion by U.S. taxpayers holding money
International students are considered nonresident aliens for U.S. tax purposes. If you receive income while in the United States—such as
IRS Form 1042-S is an annual information return for any monetary amounts given to a non-resident alien by a United States based institution or business.